Search the research desk.
Type a market, company or commodity and jump straight into the K2 report that covers it.
K2 Capital is a Hong Kong-based investment firm and a trusted channel to East and Southeast Asian investments, delivering disciplined strategies and customized portfolio solutions.
Opportunity moves across borders. K2 Capital, a trusted channel into East and Southeast Asian investments.
K2 Capital Limited · Hong Kong, China
[ What we do ]
From equities and natural gas to venture capital and franchising, across Mainland China, Hong Kong and Southeast Asia.
Read the research[ Portfolio ]
Funds, ventures and an institute across asset management, artificial intelligence, F&B and education.
Equity, commodity and thematic research from the K2 research team, on markets across Asia and beyond. Selected reports are open to everyone; clients get full access to every report.
Type a market, company or commodity and jump straight into the K2 report that covers it.
Partnerships, advisors, funds and portfolio news from K2 Capital and its companies.
Clients & recognition
[ Portfolio ]
From franchise licensing and F&B ventures to fund raises and AI acquisitions. Hover a row for a preview, select it to read the release.
[ Global Research ]
by K2 Capital Management
Gateway to strategic investment insights across Asia and beyond. Become a client to gain full access to every report.
[ News & Insights ]
by K2 Capital Management
Stay up to date with our latest news and insights.
[ Aether portfolio ]
[ Accelerators, partners and competitions ]
Press releases featuring Oliver Tedja and the firms he co-founded.
K2 Capital is advised by leaders from listed companies in China and from global financial services.
[ Contact ]
K2 Capital Limited, Hong Kong. Tell us what you are working on and the right person will get back to you.
Foreign affairs
Over 80% of world goods trade moves by sea, and Houthi disruptions have lifted freight costs by up to 30%, extended transit times by 10–14 days, and drained Egypt’s Suez Canal revenues by 40%.
Global trade rerouting remains prolonged and costly. Over 80% of world goods trade moves by sea, and continuing Red Sea disruptions have increased average transit times by 10-14 days and freight costs by up to 30%, reflecting structural congestion and higher insurance premiums. ( Atradius Collections, Gulfnews, CNN )
Freight and bunker fuel volatility will persist. Despite temporary rerouting boosts, projects bunker fuel demand to remain flat at 5 million b/d through 2030, constrained by IMO and weak trade growth. ( UNCTAD, Reuters, Ship & Bunkers )
Inflationary pressure from logistics remains a key macro risk. Rerouting via the Cape of Good Hope adds $1-1.5 billion in monthly trade losses, directly feeding into higher consumer prices and global CPI volatility. ( CNBC, CNN )
Long-term shift toward cleaner fuels and efficiency gains. IMO decarbonization policies and emerging GHG pricing (2028) will accelerate the transition to alternative fuels such as biofuels, ammonia, and hydrogen, reshaping investment across energy and logistics sectors. ( Ship & Bunkers, Reuters )
After 690 consecutive days of Houthi attacks in the Red Sea, global shipping remains unstable despite the Israel-Hamas ceasefire. The Bab- el-Mandeb-Suez Canal corridor, which handles roughly 12% of world trade, remains a conflict zone as the Houthis persist in targeting vessels linked to Israel and Western Allies ( CNBC ). In response, coordinated actions between the US, EU, China, and Australia have been established to regulate the container shipping behaviour and stabilize freight markets disrupted by rerouting through longer, costlier paths ( ITF ).
The EU’s Regional Maritime Security Programme-operational since 2021 across Djibouti, Somalia, Sudan, Ethiopia, and Yemen-works with International Maritime Organization (IMO), International Criminal Police Organization (INTERPOL), the United Nations Office on Drugs and Crime (UNODC), and the Intergovernmental Authority on Development (IGAD) to enhance regional port security and maritime domain awareness, reflecting a broader policy effort to secure critical energy and goods corridors ( IMO ). Concurrently, US sanctions may remove 500,000-600,000 barrels per day of Iranian oil by mid-2025, potentially prompting retaliatory drone and missile attacks in the Arabian Sea and Indian Ocean, extending the risk zone beyond the Red Sea ( Washington Institute ).
Heightened naval exercises by Western and Indo-Pacific allies underscore a growing securitization of global shipping, with cyber threats and maritime crimes further amplifying route instability ( Dryad Global ). The IMO sulphur cap lowered fuel sulphur limits from 3.5% to 0.5%, initially weakening high-sulphur fuel oil (HSFO) demand. Fuel oil demand falling to 6.1 million bpd by 2030, resistance to environmental regulation, US Trump administration, could delay emission policy enforcement. ( Reuters )
Global trade routes remain heavily disrupted as the Houthi conflict enters its third year. The August 2025 missile attack on the Scarlet Ray near Yanbu, Saudi Arabia, marked the first confirmed strike in the Upper Red Sea, forcing major carriers like Maersk and MSC to keep rerouting via the Cape of Good Hope. This detour has driven Suez Canal revenues down 40% since 2023-costing Egypt $ 7 billion in 2024-and pushed freight and insurance costs to multi-year highs ( Dryad Global, Gulfnews ).
Maritime trade growth is set to slow sharply from 2.2% in 2024 to just 0.5% in 2025, despite ton-miles rising 6%, triple trade volume growth ( UNCTAD ). Suez Canal throughput remains 70% below 2023, while disruptions also threaten the Strait of Hormuz, which carries a third of seaborne oil ( UNCTAD ).
Oil prices have stayed relatively stable as 80% of Gulf exports flow east to Asia, bypassing the Suez, cushioning inflation risk in Western markets ( Atradius Collections ). Meanwhile, container freight rates eased to $ 1,669 per 40-foot box due to vessel oversupply, though war-risk insurance remained elevated 0.7% of hull value. Strikingly, 63% of Houthi attacks since 2024 hit ships with no clear U.S. or Israeli link, underscoring widespread transit risk ( Gulfnews ).
Amid these conditions, Asian operators are testing the Arctic’s Northern Sea Route, halving travel time and emissions by 50%, but facing hazards from sea ice and low visibility. ( CNN )
The ongoing Red Sea disruptions have radically reshaped global fuel and trade demand flows. With vessels diverting via the Cape of Good Hope, bunker fuel consumption has surged at African and Mediterranean ports, straining infrastructure and pushing prices higher. Low-sulphur bunker fuel in Cape Town climbed 15% to nearly $800/mt, while bunker calls in South Africa rose 30%, creating congestion at Durban, Port Louis and Gibraltar. Mauritius’s Port Louis saw bunker sales double to 1 million mt in 2024, up from 500,000 mt in 2023, benefiting from the closure of Algoa Bay’s offshore bunkering operations. ( Reuters, Ship & Bunker )
Tanker freight rates remain elevated following incidents such as the attack on the Magic Seas, with longer voyages, insurance, surcharges, and reduced fleet availability tightening supply. Alternative bunkering hubs like Sohar, Dammam, and Colombo have seen rising ship-to-ship transfers, while Oman’s VLSFO supply constraints pushed local premiums to $33/mt above sohar prices. Although Strait of Hormuz traffic remains stable under heavy naval presence, tensions between Israel and Iran continue to weigh on tanker movements and regional pricing. ( S&P Global )
Globally ship diversions have added roughly 100,000 bpd of fuel oil demand, equivalent to 2% of total bunker demand, according to FGE, while the IEA reported a smaller 140,000 bpd annual increase in 2024 due to high freight costs and weak trade growth. Despite these short-term boosts, the IEA projects global bunker demand to plateau at 5 million bpd through 2030, constrained by IMO decarbonisation rules and sluggish globalisation.The newly established Mediterranean SECA zone (May2025) and upcoming global GG pricing system (2028) are expected to accelerate the shift from conventional marine fuels toward biofuels, ammonia, and hydrogen,gradually eroding demand for traditional fuel oil. ( Reuters, Ship & Bunker )
In 2024, vessels rerouted Africa due to the Red Sea Crisis coupled with the offshore bunkering shutdown in Algoa Bay. led to a significant surge in bunker sales at Port Louis, Mauritius. Bunker Fuel sales in Port Louis neared 1 million mt in 2024, doubling 500,000 mt in 2023 and more than triple the 300,000 mt recorded in 2015, Durban-based Linsen Nambi shared in its linkedin post from a presentation at maritime week africa, taking place in mauritius. VLSFO accounted for 65% of the total bunker sales in 2024, followed by 23% HSFO and 12% MGO. HSFO share doubled from 12% in 2023, indicating increased demand from scrubber-fitted vessels. The presentation mentioned that the closure of offshore bunkering in Algoa Bay benefited Port Louis to cater to increased demand from vessel diversions. Offshore bunkering in Algoa Bay was shut down in mid-September 2023 after the South African Revenue Services (SARS) detained five vessels, including bunker barges, for customs duty disputes. ( Ship & Bunker )
Global maritime chokepoints underpin commodity price stability. The Red Sea-Suez Canal corridor, carrying 15% of global trade and 30% of container traffic, and the Strait of Hormuz, which moves 20.9 million b/d (20% of global oil), have seen major disruptions since late 2023. Suez crude and product flows fell 50% YoY (from 7.9 to 3.9 million b/d), forcing diversions around the Cape of Good Hope, adding 10-14 days and $1-1.5 million in additional voyage costs per vessel. ( CNBC, CNN )
These diversions lifted VLCC freight rates by + 154WoW, LR2 tanker rates by +148%, and marine insurance premiums by +60%, while bunker prices at Cape Town surged 15% to $800/mt. The rerouting added 100,000 b/d of global bunker fuel demand (+2%) but reduced Red Sea transits from 70/day to 28/day, according to IMF PortWatch. ( S&P Global )
Operational risk is climbing as older vessels with unverified insurance dominate rerouted lanes, increasing spill and accident exposure. Naval deployments and higher security costs are now embedded in global freight pricing models, creating a sustained premium on maritime trade. In effect, shipping disruptions are not temporary shocks but structural cost amplifiers across energy, manufacturing, and consumer goods supply chains. ( Bloomberg, Dryad Global, Resilinc )
The Red Sea crisis has amplified logistics risk at a time when 80% of global trade depends on maritime routes. Since late 2023, diversions from the Suez Canal to the Cape of Good Hope have extended voyages by 10-14 days and raised freight costs by 25-30%, with war risk premiums up from 0.3% to 0.7% of hull value. Insurance surcharges averaging $5,000 per voyage and higher bunker consumption (+15%) have directly filtered into final import prices. ( CNN )
As of mid-2025, over 100 vessels have rerouted around Africa compared to fewer than 60 in December 2023. Freight rates on the European-Mediterranean route doubled to $3,700/FEU, while the Israeli and Red Sea routes exceeded $6,000/FEU. Transit times from China to Europe rose 25%, and to the U.S. East Coast 47%, pressuring just-in-time manufacturing and retail supply chains. ( Resilinc )
Container turnaround inefficiencies now extend average TEU-miles by 16%, according to Sea-Intelligence, tightening global container availability despite subdued manufacturing demand. Simultaneously, port congestion surged at alternative hubs-bunker sales in Port Louis nearly doubled to 1 million mt, while Djibouti activity fell 58%. ( Freight Mango, S&P Global )
Fuel logistics and freight capacity have realigned: ship-to-ship transfers increased by 88% in Mumbai and 47% in Sohar, reflecting regional adaptation but infrastructure strain. In parallel, Panama Canal drought constraints compound global delays, creating a dual chokepoint shock that limits rerouting flexibility and raises macro-supply risk. (Project44)
Track monthly crude + petroleum product flows through the Suez Canal: dropped from 7.9 million b/d in 2023 to 3.9 million b/dd in 2024. Bab el-Mandeb Strait transit shipments fell from 70 vessels/day pre-war to 28 vessels/day in July 2025. If drop above 40% compared to the previous year signals major rerouting pressure. ( S&P Global )
Hull war-risk surcharges rising from 0.3% of hull value before peak attacks to 0.7% during intense attack periods. Fixed voyage surcharges reaching $5,000+ per transit for U.S./Israeli-affiliated ships in Red Sea areas. If above 0.5% signals a high cost regime; doubling indicates extreme perceived risk. ( CNN )
Cape Town low-sulphur bunker price jumped 15% to nearly $800/mt since mid-November 2024. Port Louis bunker sales doubles: 1,000,000 mt in 2024 vs 500,000 mt in 2023.VLSFO and HSFO share shifts: in Port Louis, VLSFO = 65% of sales in 2024, HSFO up from 12% to 23%. If Price spikes above 10% and port sales volumes rises above 50% signal demand shift. ( Reuters, Ship & Bunker )
Container freight: Shanghai-Europe / Mediterranean routes doubling in price to $3,700-6,000 FEU for some rerouted lanes. VLCC and LR2 tanker spot rates up 154% and 148% WoW on certain Middle East -> Asia or Japan routes. Transit times from China to Europe increased by 25%, China to the U.S. East Coast by 47%. If freight rate increases above 100% WoW or transit time increases above 25% vs baseline indicate serious cost pressure. ( S&P Global, Resilinc )
Ton-miles (total cargo distance x weight) up to 6% in 2024, nearly three times the trade volumes in 2023 (2.2%). TEU-miles increased by 16% per Sea-Intelligence reports, indicating containers are spending more time & distance in transit (reduced availability). If TEU/ton-mile growth exceeding trade volume growth by factor above 2 signals structural inefficiency. ( UNCTAD, Freight Mango, S&P Global )
( Ship & Bunker, UNCTAD, CNBC, Washington Institute, Reuters )
( CNN, Atradius Collections, CNBC, Reuters, Resilinc, Dryad Global, Gulfnews )
( CNBC, Ship & Bunker, Reuters, UNCTAD, CNBC, CNN )
Become a client to gain full access to every K2 report.
Why the component accounting for 30–50% of humanoid robot cost is the highest-conviction investment in the next industrial revolution.
Kuaishou Technology is China’s second-largest short video and live streaming platform, with 401 million daily active users and 735.6 million monthly active users as of Q4 2024.
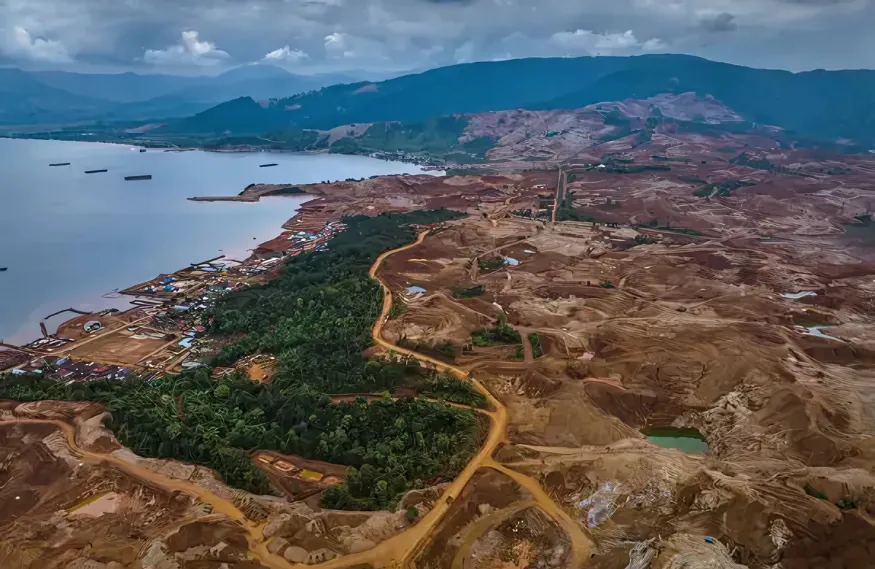
How Jakarta’s resource nationalism is reshaping EV supply chains, LME pricing and the geopolitics of critical minerals, and where capital should be positioned.